
The Speed Advantage of Being Small
Australia’s major banks have the balance sheets, the customer bases, and the regulatory relationships. What they do not have — at least historically — is the speed to ship new payment capabilities. That gap has created an opening for fintechs to build A2A infrastructure that banks have been slow to deliver.
Volt has become one of the most aggressive players in this space. In February 2026, the company achieved NPP Identified Institution status, giving it direct access to the New Payments Platform and the ability to register PayIDs and offer PayTo services. By October 2026, Volt had obtained an Australian Financial Services Licence from ASIC, completing a regulatory trifecta across the UK, EU, and Australia.
The licence authorises Volt to provide A2A payment services — both pay-ins and pay-outs — on the NPP to retail and wholesale clients in Australia. This is not a partnership arrangement or a white-label service. It is direct infrastructure access, which means Volt can compete with banks on capability rather than simply on user experience.
AI-Initiated Payments: The Next Frontier
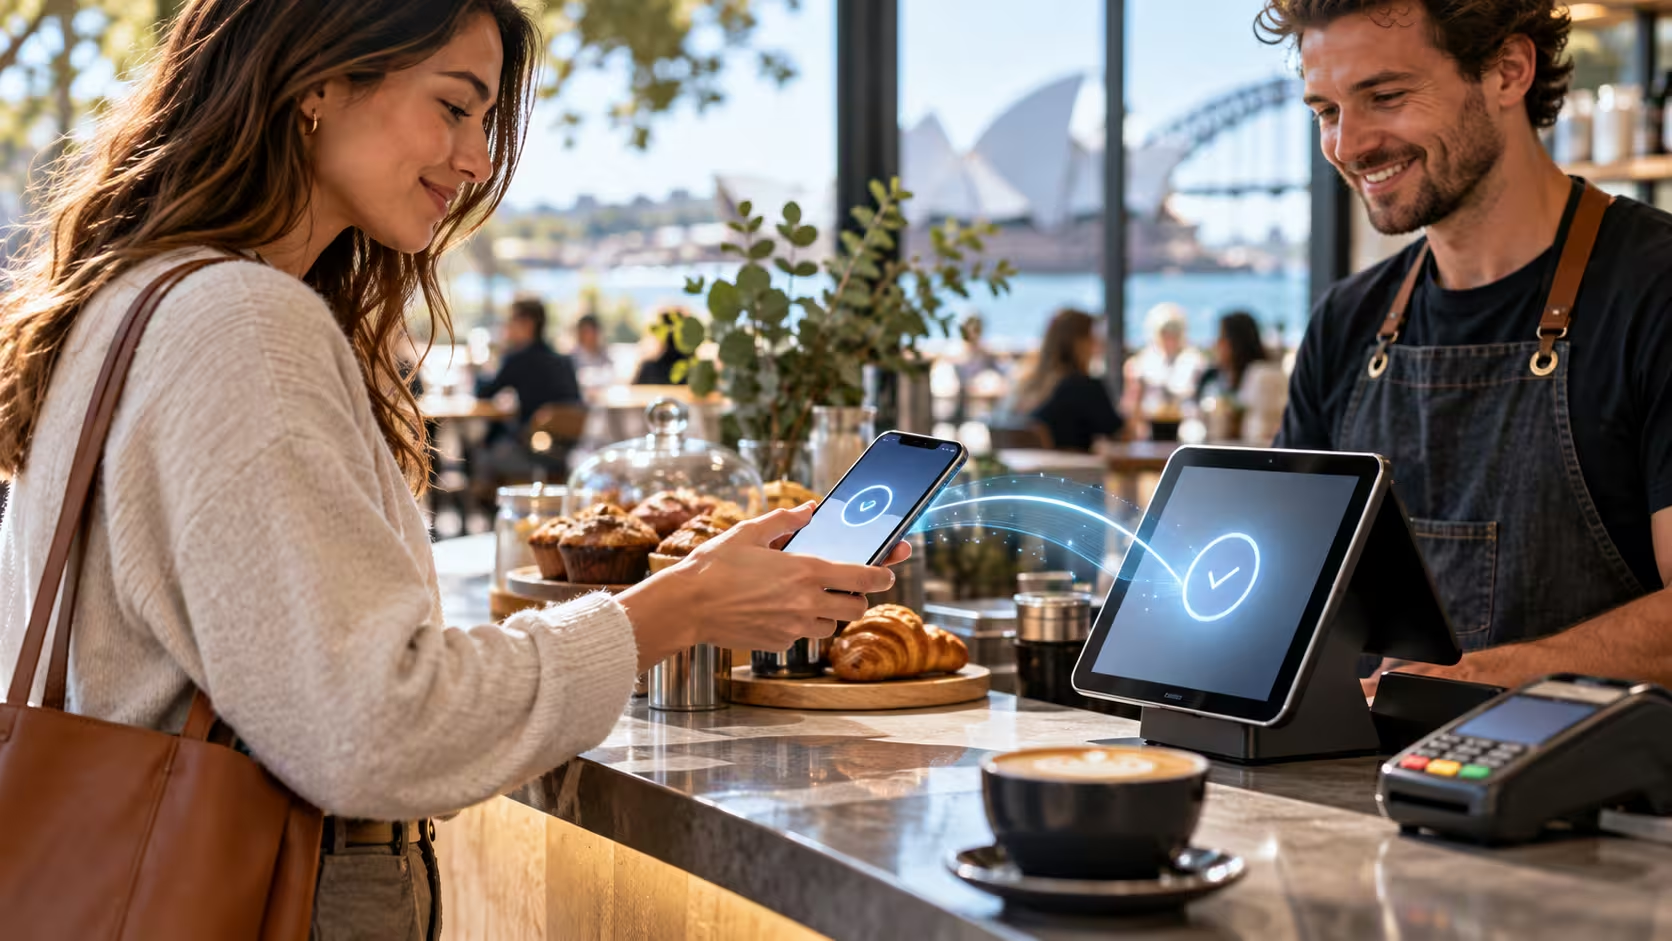
If direct NPP access is the foundation, AI-initiated payments are the differentiator. In June 2026, Vivi Money demonstrated an AI-initiated A2A payment experience operating over Australia’s NPP infrastructure.
The demonstration showed a customer issuing a natural-language instruction — via text or voice — that triggers a payment to an external bank account without requiring manual entry of BSB codes or account numbers. The system interprets the instruction, identifies the recipient, and initiates the payment through the NPP.
This is not a gimmick. It addresses one of the most persistent friction points in A2A payments: the lack of a universally recognised identifier at the point of payment. PayID solves this for peer-to-peer transfers, but integrating natural-language payment initiation into commercial contexts opens possibilities that card networks cannot easily replicate.
Why Banks Are Playing Catch-Up
The structural reason for the fintech advantage is straightforward. Banks operate under legacy technology stacks that were designed for batch processing and card networks. Modifying core banking systems to support real-time, API-driven A2A payments is expensive, risky, and slow.
Fintechs, by contrast, build on modern cloud infrastructure from day one. They can integrate with the NPP through APIs, iterate quickly, and deploy new capabilities without waiting for a core banking upgrade cycle.
This does not mean banks are irrelevant. They hold the customer deposits and the regulatory licences that fintechs need for certain activities. But the balance of power in A2A innovation is shifting toward smaller, faster-moving organisations.
The Competitive Landscape Ahead
The A2A Payments Roundtable’s vision explicitly calls for a payments system that is “accessible for providers”. That language is not accidental. It reflects an industry consensus that competition in A2A payments should not be limited to the four major banks and their subsidiaries.
Fintechs like Volt and Vivi Money are testing whether the NPP can support a genuinely competitive payments market — one where innovation happens at the edge, not at the centre. If they succeed, the legacy card networks will face a competitor that is cheaper, faster, and more adaptable.
The infrastructure is in place. The regulatory frameworks are maturing. The only question is how quickly consumers and merchants will reward the fintechs that got there first.