
The Unintended Revival
When the RBA designed its surcharge ban, the policy brief was about transparency and simplicity. What it did not anticipate—or at least did not foreground—was a quiet resurgence of physical currency as a strategic tool. Within a week of the 1 October 2026 changes, one Australian supermarket reported a 30 per cent increase in cash sales, attributing the jump directly to the new pricing environment. That is not a nostalgic blip. It is a behavioural response to a structural change, and it has created a set of winners that few predicted.
The Cash-Discount Playbook
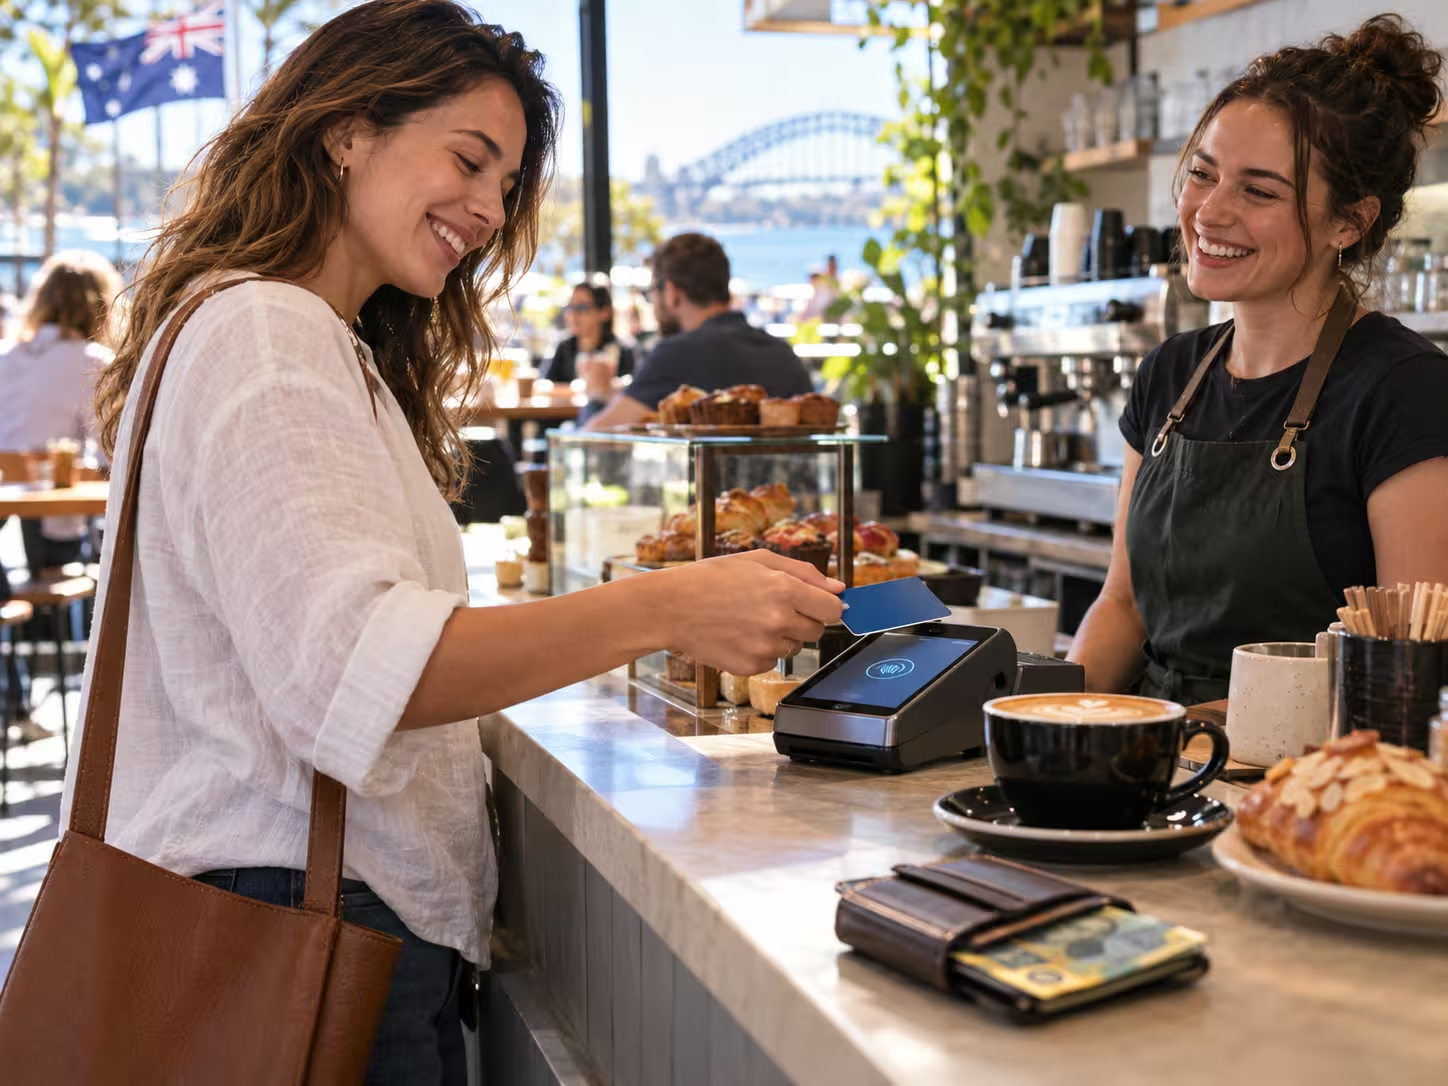
The mechanism is straightforward. The ACCC confirmed that businesses can legally offer discounts to customers who pay with cash, provided the displayed price reflects the full amount a customer would pay without the discount. For merchants, cash eliminates card processing costs entirely. For consumers, the discount is a visible, immediate reward for a behaviour that had been steadily declining for two decades. The result is a two-tier pricing system that operates within the law but outside the spirit of a ban designed to make prices simpler.
Small businesses have been quick to experiment. Some have erected “CASH PREFERRED” signage; others have trained staff to mention the discount at the point of sale. For operators who spent years watching card fees erode their margins, the cash option is not ideological—it is a rational response to a cost structure that the surcharge ban did not eliminate, only relocate.
The Psychology of Paying
The deeper shift is psychological. Card payments are frictionless, almost invisible; the money leaves without the tactile feedback of handing over notes. Surcharges, for all their annoyance, made the cost of payment visible. Removing them has, paradoxically, made some consumers more conscious of the cost of acceptance—not because they see a fee, but because they are now offered a discount to avoid it. Behavioural economists have long noted that framing matters: a surcharge feels like a penalty, while a discount feels like a reward. The surcharge ban has replaced one frame with the other, and early evidence suggests the discount frame is more effective at driving cash usage than the penalty frame ever was.
The Losers in the Shadows
Not everyone benefits from the cash revival. Consumers who rely exclusively on cards—a growing demographic, particularly among younger Australians—cannot access the discounts and may effectively subsidise the pricing structure through higher embedded prices. The RBA’s own data suggests that about half of Australians used no cash in a typical week even before the ban. For them, the surcharge ban delivered a cleaner receipt but not necessarily a cheaper one.
There is also a regulatory risk lurking beneath the surface. If cash discounting becomes widespread enough to function as a de facto surcharge on card users, the ACCC and the RBA may face pressure to revisit the rules. The line between a legitimate discount and a disguised penalty is thinner than it appears, and businesses operating near that line will need to document their pricing logic carefully.
The New Payment Settlement
The surcharge ban was sold as a consumer victory, and in many ways it is. But the early evidence reveals a more complicated settlement: banks are repricing, merchants are restrategising, and consumers are rediscovering the tactile appeal of a $20 note. The cash comeback is not a rejection of digital payments. It is a signal that when the rules change, behaviour follows—often in directions that policymakers did not map. The winners of Australia’s surcharge ban are not just the households that save a few cents at the register. They are the businesses that understood, early, that the cost of payment never disappears—it only moves.